
Buying an existing business can be an attractive alternative to starting from scratch. Instead of building a customer base, developing systems and waiting for revenue to grow, an acquisition can provide access to an established operation, existing customers, employees and proven revenue.
But one of the biggest questions for Canadian entrepreneurs is:
The answer depends on the purchase price, business cash flow, assets being acquired, your own financial position and the structure of the transaction.
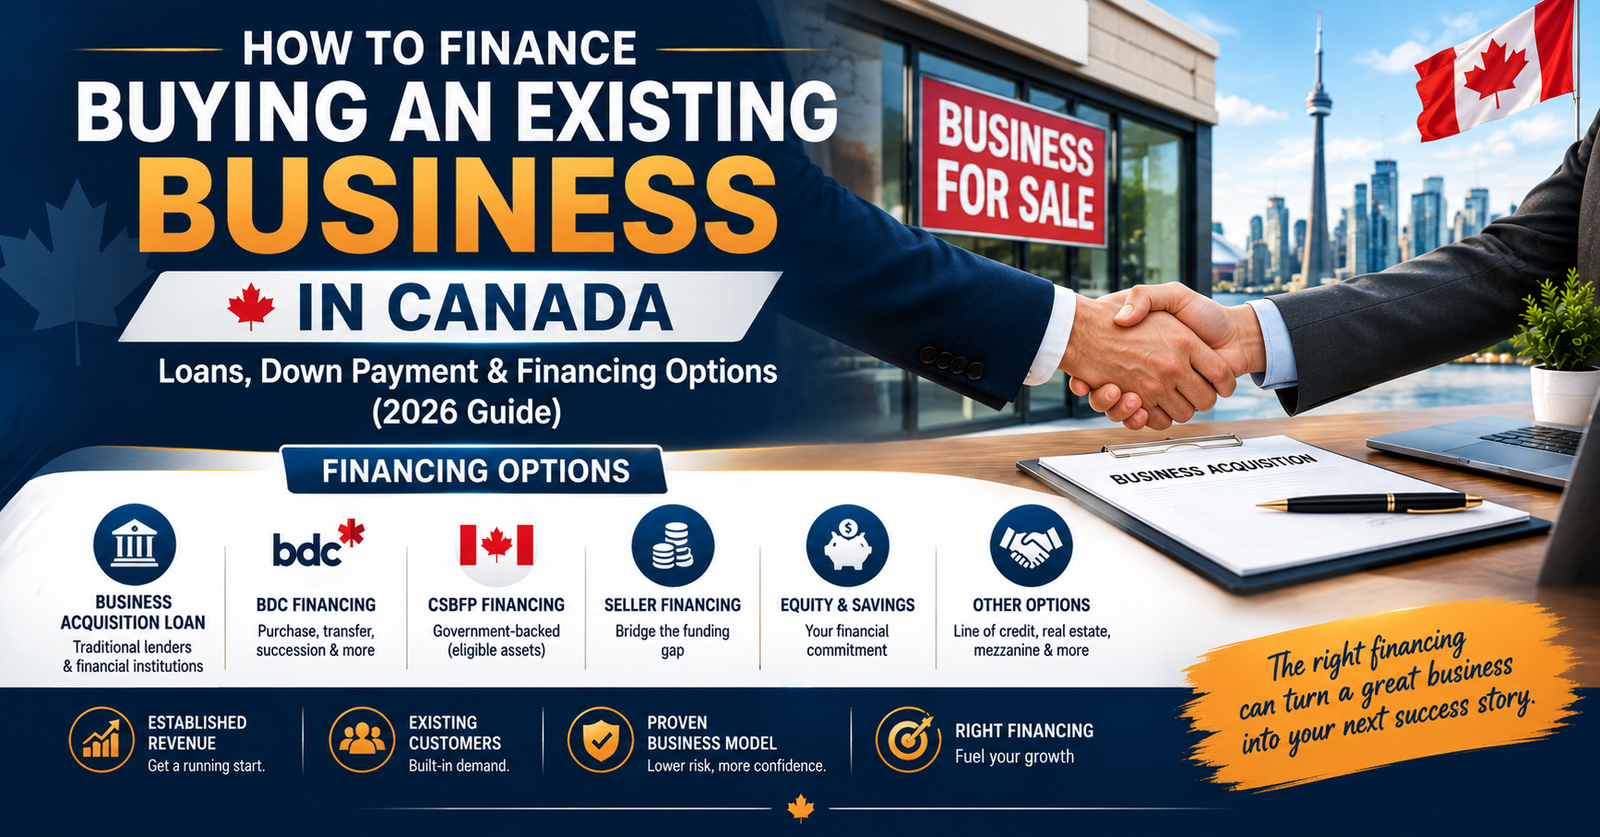
Canadian buyers can potentially use a combination of business acquisition loans, BDC financing, CSBFP financing, seller financing, personal equity, commercial financing and other forms of business funding.
This guide explains the major options and what lenders typically look at before approving acquisition financing.
Yes.
Financing is available for eligible business acquisitions, although lenders generally want to see a strong case that the business can generate enough cash flow to support the proposed debt.
For example, BDC currently offers Business Purchase or Transfer Financing for transactions involving an existing Canadian business that is generating revenue. Its financing can be used for acquisitions, competitor or supplier purchases, management or employee buyouts, family-business transfers and certain related acquisition costs.
The structure of the transaction matters considerably.
A lender may distinguish between:
An established business can provide several advantages.
Existing Revenue
You may acquire a business that already has paying customers and historical revenue.
Established Customer Base
You don’t necessarily have to build your customer base from zero.
Existing Operations
The business may already have:
Proven Business Model
Historical financial statements can provide evidence of how the business has performed.
However, an existing business isn’t automatically a good investment. The buyer still needs to conduct thorough financial, legal and operational due diligence.
There is no universal down-payment percentage that applies to every Canadian business acquisition.
The required equity contribution can depend on:
Your financing structure could potentially combine several sources of capital.
For example:
Purchase Price: $1,000,000
Possible structure:
This is only an illustrative structure—not a standard lending formula.
The actual financing package needs to be determined based on the transaction and lender requirements.
A dedicated business acquisition loan can be one of the most appropriate financing options when purchasing an established company.
The lender evaluates both:
The buyer
and
The business being purchased.
The business’s historical financial performance becomes particularly important because lenders need confidence that the acquired company can generate sufficient cash flow to service the debt.
BDC specifically offers financing for buying or transferring an existing business.
Its current Business Purchase or Transfer Financing can potentially help finance:
BDC also indicates that legal fees, moving expenses and other one-time acquisition costs can potentially be included in its financing.
For a BDC application, you should be prepared to provide information such as:
BDC currently states that the business being purchased must be located in Canada and generating revenue.
The Canada Small Business Financing Program (CSBFP) can also be relevant to certain business acquisitions.
However, there is an important distinction.
CSBFP financing does not simply finance the purchase price of an entire company.
Under the current program rules, the purchase of eligible assets of an existing business may qualify. The amount that can be financed is generally limited to the lesser of the purchase cost and the appraised value of the eligible assets.
This distinction is critical when structuring an acquisition.
Example
Suppose you’re buying a company for:
$750,000
The transaction includes:
Not every component necessarily receives the same treatment under CSBFP rules.
The lender needs to determine which assets are eligible and how the acquisition is structured.
Generally, no.
CSBFP rules distinguish between acquiring eligible business assets and acquiring shares.
The official program guidance states that the acquisition of shares is not eligible for CSBFP financing. (Innovation Canada)
This is one reason why the difference between an asset purchase and a share purchase should be discussed with your lawyer, accountant and financing provider before signing the transaction documents.
Seller financing—sometimes called vendor take-back financing—can be another component of an acquisition financing package.
Under this arrangement, the seller finances part of the purchase price.
For example:
Business purchase price: $1,000,000
Seller financing can help bridge a funding gap between the buyer’s available equity and the total purchase price.
However, its structure, ranking and terms need to be carefully negotiated.
Also note that seller financing has specific treatment under CSBFP rules; vendor take-back financing itself is not eligible expenditure for a CSBFP loan.
Most acquisition financing structures require the buyer to demonstrate some level of financial commitment.
This can come from:
Putting your own capital into the transaction demonstrates financial commitment and can reduce the amount of debt required.
A business line of credit may be useful for post-acquisition working capital, even if it isn’t the primary acquisition financing.
For example, after buying a company, you may need funds for:
This is especially important because a buyer shouldn’t assume that all available cash should be used toward the purchase price.
Maintaining adequate working capital after closing can be just as important as completing the acquisition itself.
If the acquisition includes a commercial property, separate real-estate financing may be appropriate.
For example, you may be purchasing:
Separating the real-estate component from the operating business can sometimes create a more appropriate financing structure.
This is where many buyers make mistakes.
Lenders don’t simply ask:
“How much does the business cost?”
They want to understand:
“Can this business generate enough cash flow to repay the proposed financing after the acquisition?”
Lenders will typically want to see the company’s historical sales.
They may examine:
Stable revenue can provide greater confidence than highly unpredictable sales.
Revenue alone doesn’t tell the whole story.
A company generating $2 million in annual sales but very little profit may be less financeable than a company generating $1 million with strong margins.
Lenders may examine:
Cash flow is particularly important in acquisition financing.
The lender needs to understand whether the business can service:
Existing operating expenses + new debt payments + required working capital.
This is why a profitable-looking business can still have financing challenges if its cash flow is weak.
Buyers and lenders need to determine whether reported earnings are sustainable.
For example, a seller might report unusually high profit because certain expenses were temporarily reduced.
A proper analysis should identify:
The lender isn’t only financing the business.
It is also financing you as the new owner.
Your:
can influence how the lender evaluates the transaction.
The lender will want to understand why the business is worth the proposed purchase price.
You should be able to explain:
BDC recommends understanding valuation and how price relates to the business before completing an acquisition.
One of the most important questions is:
Are you buying the assets or the shares?
An asset purchase means you acquire specified assets and potentially assume specified liabilities according to the transaction agreement.
A share purchase means you acquire ownership of the corporation itself.
The tax, legal, financing and liability implications can be significantly different.
Always involve qualified legal and accounting professionals before choosing the structure.
Documents You Should Prepare
A professional acquisition financing application should be well organized.
Buyer Documents
Prepare:
BDC currently asks acquisition-financing applicants for Notices of Assessment for the previous two years.
Target Business Documents
Depending on the lender and transaction:
Transaction Documents
You may need:
BDC specifically lists the agreed purchase price, transaction structure, letter of intent, expected closing date and required down payment among information applicants should be prepared to provide.
Due Diligence Before Applying for Financing
Don’t rush to the lender before understanding the business.
A proper acquisition due-diligence process should examine at least:
Financial
Legal
Commercial
Operational
Tax
A financing approval doesn’t automatically mean the acquisition is a good investment.
A $500,000 acquisition doesn’t necessarily require only $500,000.
You may also need funds for:
Leaving yourself with no liquidity after closing can create serious cash-flow problems.
Seller financing can sometimes help bridge a funding gap and align the seller with a successful transition.
The business may perform differently after ownership changes.
Customer relationships, employees and suppliers may react differently to the transition.
Before approaching lenders, know:
Example: Financing a $1 Million Business Acquisition
Consider a hypothetical Canadian company generating stable revenue and producing strong cash flow.
Purchase price: $1,000,000
Potential financing structure:
Source | Amount |
Buyer equity | $200,000 |
Senior financing | $600,000 |
Seller financing | $200,000 |
Total | $1,000,000 |
The buyer would then need to ensure adequate working capital remains available after closing.
This is only an illustration. Actual financing structures vary significantly based on the business, lender, transaction and buyer.
Buying a business with zero personal equity can be challenging.
A lender generally wants to see that the buyer has some financial commitment to the transaction.
However, acquisition structures can sometimes combine:
BDC notes that acquisition financing can involve a combination of equity investment, senior debt, vendor debt and mezzanine financing depending on the transaction.
The objective is to create a capital structure that allows the business to remain financially healthy after closing.
Stable historical cash flow generally makes financing easier to justify.
Industry experience can strengthen your credibility.
Show:
A strong business can become a poor investment if you pay too much.
Don’t put every available dollar into the purchase.
Give lenders a clear picture of:
There isn’t one lender that is best for every acquisition.
Traditional Bank
Potentially suitable for:
BDC
Potentially useful for:
BDC currently offers dedicated Business Purchase or Transfer Financing for qualifying acquisitions.
CSBFP
Potentially useful when the transaction involves eligible assets and meets the program’s requirements.
However, the participating financial institution makes the lending decision, and share purchases are not eligible under the program.
Buying an existing business can provide a faster route to entrepreneurship than building a company from the ground up—but financing the acquisition requires careful planning.
The strongest acquisition proposals typically demonstrate:
There are several potential financing sources, including business acquisition loans, BDC financing, CSBFP financing, seller financing, commercial real estate financing and equity investment.
The most important step is to structure the financing around the business’s ability to generate cash flow—not simply around the purchase price.
If you’re considering buying a Canadian business, start preparing your financial information and transaction structure before making a binding commitment.
Yes. Several financing options can potentially be used, including business acquisition loans, BDC financing, bank financing, seller financing and other forms of acquisition capital.
The CSBFP can potentially finance the purchase of eligible assets of an existing business, subject to program requirements. The purchase of shares is not eligible under the program.
Yes. BDC currently offers Business Purchase or Transfer Financing for qualifying Canadian businesses that are generating revenue.
There is no universal down-payment requirement. It depends on the lender, business, transaction structure, purchase price and buyer’s financial position.
Yes, seller financing can be part of an acquisition financing structure. However, its treatment can vary by financing program and transaction structure.
It can be more difficult, but financing may still be possible depending on the strength of the business, cash flow, buyer’s overall financial position and lender.
In negotiations, I’ll represent you. When it comes to discussing mortgages with their bank, many customers are unsure or uneasy. Even if you have an existing relationship with your branch, I can use that relationship to your advantage when negotiating your mortgage, ensuring that you get the best rates and terms possible. Call me right now for a free, no obligation consultation. Call +1 (431) 999-8485 or Apply now!